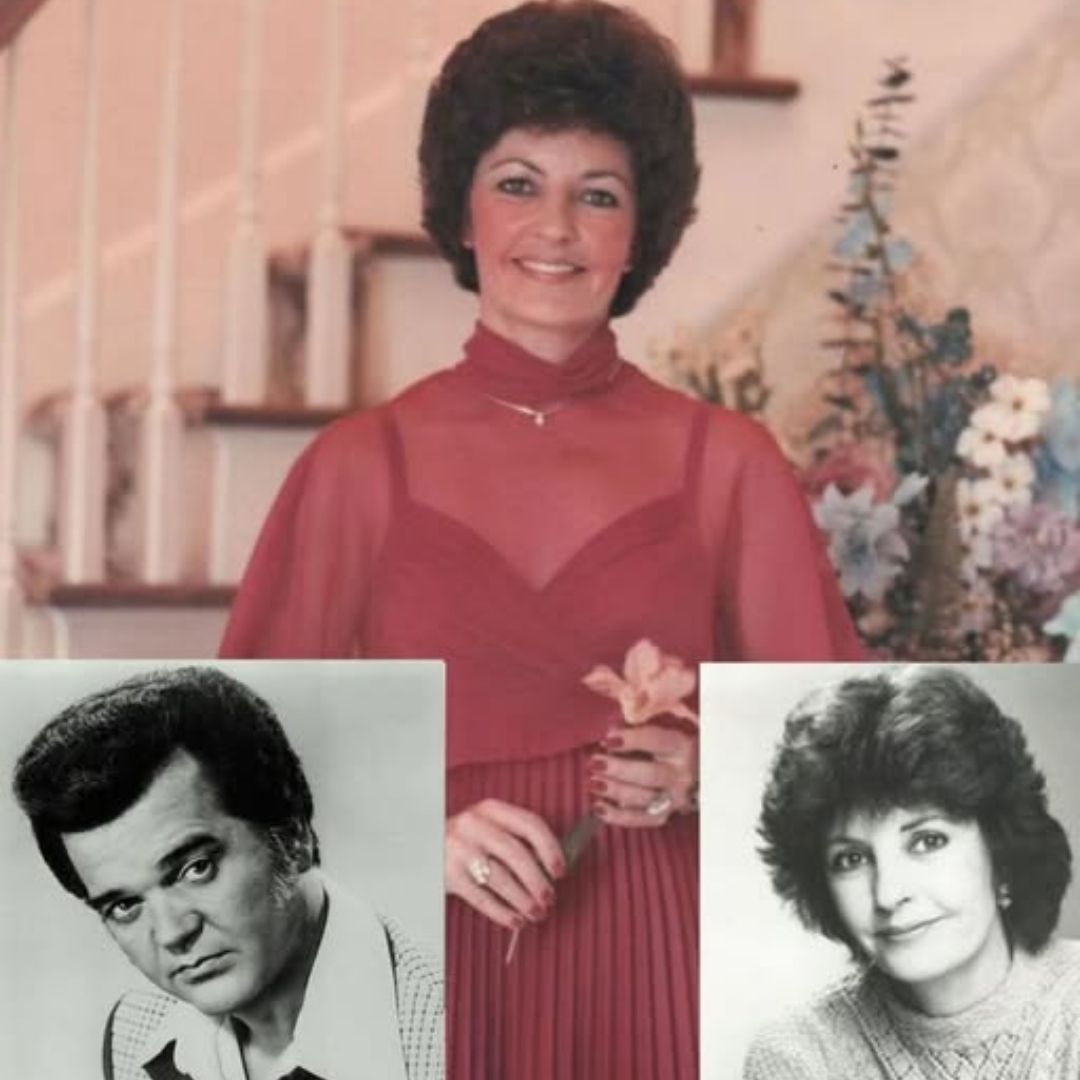
AFTER CONWAY TWITTY DIED, HIS FAMILY HAD TO BID FOR THE LIFE HE LEFT BEHIND
The auction crew wore tuxedos and white gloves. Beneath a large white tent in Hendersonville, every chair appeared to be occupied. License plates in the parking lot came from well beyond Tennessee.
For three days in October 1994, auctioneers moved through the contents of Conway Twitty’s life. Stage guitars and performance clothes carried obvious value. So did his automobiles and jewelry. Then came office furnishings, household objects, a jukebox and the Christmas decorations that had once belonged to the private life inside Twitty City.
Fans had previously entered those grounds to feel closer to Conway. Now they arrived carrying bidder numbers.
His widow was among them. By the time the sale ended, she had spent nearly $80,000 acquiring a car, jewelry and the jukebox from the estate of the man with whom she had lived.
A City Built Around One Voice
Conway Twitty had never treated success as something that existed only on records. During the early 1980s, he built an extensive complex in Hendersonville, north of Nashville, and placed his professional name over its entrance.
Twitty City contained Conway’s large home, residences for his mother and children, business offices, landscaped grounds, a theater, museum displays, shops and places where visitors could look across the physical history of his career. Contemporary estimates put the original cost near $3 million.
The arrangement blurred several boundaries at once. Twitty City was a tourist attraction, but it was also where the family lived. It offered fans access, yet Conway’s private home remained at its center. The gold records, costumes and photographs represented a public career; the nearby houses held the people for whom that career was supposed to provide.
Conway had reason to believe the structure could endure. His success had already survived rock and roll, several changes in country production and the arrival of younger radio stars. Beginning with “It’s Only Make Believe” in 1958, he had crossed from pop stardom into an even longer country career. “Hello Darlin’,” “Linda on My Mind,” “I’d Love to Lay You Down” and his duets with Loretta Lynn kept his voice on the radio through decades that retired many of his contemporaries.
When Twitty City opened, it gave that continuity an address. A fan could travel to Hendersonville and see a career translated into buildings, gardens and rooms.
The buildings would prove easier to sell than the history inside them.
The Last Ride From Branson
On June 4, 1993, Conway performed at the Jim Stafford Theatre in Branson, Missouri. Accounts from the period indicate that he was already suffering severe abdominal pain, but he completed the appearance.
Afterward, the bus headed toward Nashville, where Fan Fair was underway. Conway collapsed on the road and was taken to a hospital in Springfield. Doctors discovered a ruptured abdominal aneurysm. Surgery could not save him. He died early the next morning at 59.
The suddenness left almost no interval between an active touring career and the administration of an estate. Conway had not retired into a quiet period in which businesses, properties and rights could be gradually separated. His final album, later released under the title Final Touches, had already been recorded. Royalties were still arriving. Companies still bore his name. Twitty City remained both a commercial attraction and a collection of family homes.
Country music obituaries could count the No. 1 records and describe the voice. Probate required different nouns: beneficiary, insurance proceeds, secured debt, appraisal, elective share and future income.
Harold Lloyd Jenkins had died. The legal system now had to establish the value of Conway Twitty.
What the Will Said
The probate record is more precise than the later language of “family feud.”
Conway’s will and two codicils provided $50,000 for his mother, Velma Dunaway. The remainder went to his four adult children: Joni, Kathy, Jimmy and Michael Jenkins.
His surviving spouse, Dolores Henry Jenkins—known as Dee—was not left the remainder of the estate. Tennessee law, however, allowed a surviving spouse to elect against a will and claim a statutory share. In December 1993, Dee filed a petition to do so.
Her claim did not automatically establish one simple cash figure. The estate contained real property burdened by debt, insurance arrangements involving Conway’s former wife, personal property, business interests and intellectual rights expected to generate income for years.
The disagreement therefore extended beyond who received which object. The parties disputed what belonged inside the estate’s net value, whether secured debts should reduce that calculation, how income earned while probate continued should be divided and how to value future royalties.
These were legal questions with intimate consequences. A court’s ruling on an accounting method could determine who controlled the home, who received income from the records and how much of the estate had to be converted into cash before anyone could receive a share.
The Sale of the Family Address
By June 1994, Trinity Broadcasting Network had agreed to purchase Twitty City for a reported $2.75 million. TBN already owned adjacent property and planned a larger gospel and country entertainment complex with television production facilities.
The sale covered much more than a recognizable tourist sign. Twitty City included the residences occupied by Conway’s mother and his adult children. Under the purchase agreement, the family members living there would have to leave.
That detail changes the meaning of the transaction. This was not simply the sale of an unprofitable museum after its featured artist had died. A commercial landmark and a family address had been constructed on the same ground. Liquidating one displaced the other.
TBN later renamed the property Trinity Music City. Some elements of Conway’s presence remained visible for years, and tours of his house continued under the new ownership for a time. But the organizing idea had changed. The complex no longer belonged to the family or operated as the physical center of Conway Twitty’s career.
The name over the property could be replaced. The contents still had to be dealt with.
Three Days Beneath the White Tent
The public estate sale was scheduled for October 14–16, 1994. Advance coverage advertised guitars, stage clothing, jewelry, automobiles, office furnishings and thousands of additional pieces.
Retrospective recollections from an auction worker describe an unusually formal production: workers in tuxedos, white gloves, a packed tent and extensive media attention. The presentation acknowledged that ordinary household liquidation had crossed into public ceremony.
Yet the auctioneer still had to call numbers.
A performance guitar could be separated from the hands that had played it. A rhinestone garment could be separated from the stage lights for which it had been made. Office furniture, family possessions and decorations acquired over years could be grouped into lots and assigned minimum bids.
Contemporary reports differed slightly on the item count, but the final accounts placed it above 3,000. Fans, family members and collectors spent more than $1 million. Organizers had expected roughly half that amount.
Conway’s fame increased the value of the objects while helping scatter them. A private buyer could want the same guitar a museum might have preserved. A fan could place more emotional value on an object than an appraiser. Once every lot was sold, no single institution retained the collection as a complete record of how Conway had worked and lived.
Years later, items from that weekend would appear at new auctions with their 1994 certificates of authenticity. The first sale had not ended their movement. It had begun it.
The Widow’s Bidder Number
The report that Dee spent nearly $80,000 deserves restraint.
It is tempting to reduce the scene to a widow “buying back her own belongings.” Probate ownership is more complicated than that phrase allows. The objects belonged to the estate, and purchasing them at auction established clear possession while turning their value into money available for distribution.
Still, the human shape of the transaction is difficult to ignore.
Jewelry that had existed inside a marriage became a lot. A car became a lot. A jukebox that had occupied the world the couple shared became a lot. To keep them, Dee entered the same process as collectors who had known Conway only through records and concerts.
Her bids also prevent the story from being divided too neatly into grieving children on one side and an outside claimant on the other. Dee had a legal right as the surviving spouse. Conway’s children had a will naming them as the principal beneficiaries. Both claims could be legitimate while remaining financially incompatible.
Probate does not require a villain to dismantle a household. It needs only valuable property, competing rights and no agreement about how the parts should be divided.
The Auction No Fan Could Attend
The public sale disposed of objects. The more consequential bidding concerned assets no one could display under a tent.
Conway’s intellectual property included the right to receive songwriter royalties, recording-artist royalties and income from licensing agreements. Unlike a stage suit, these rights could continue producing money while the estate remained unsettled.
A professional appraisal estimated their fair-market value based partly on expected income over the following twenty years. The probate court then created a bidding process between Dee and Conway’s children. Bidding would begin at the appraised amount and rise in $1,000 increments. The winner would receive the intellectual property, with the winning figure charged against that side’s portion of the estate.
The four children combined their position and submitted the highest bid.
This was a very different kind of inheritance. They were beneficiaries under their father’s will, yet retaining control of his musical property required them to place a competitive value on it. Songs associated with family memory became projected revenue streams. Future uses of Conway’s voice became part of a courtroom calculation.
The resulting litigation did not end quickly. Appellate opinions years later were still determining how income generated during the long administration should be divided and whether particular payments belonged inside the surviving spouse’s elective share.
Meanwhile, the catalog continued earning.
The Years the Estate Took Away
Conway was inducted into the Country Music Hall of Fame in 1999, six years after his death. That honor arrived while major questions surrounding the estate were still being litigated.
His official biography now describes the legal battle as a reason his children were unable for years to undertake the reissues, archival projects and retrospectives they believed his career deserved. Their difficulty was not a shortage of material. Conway had left recordings, performances, business records and an enormous audience.
The problem was authority.
Who could approve a release? Who received the royalties? Who controlled the name, recordings and compositions? Which income belonged to the period before an appraisal, and which belonged to the eventual owner of the rights? Until those questions were resolved, remembrance itself had a financial structure underneath it.
This is one reason estate planning becomes part of music history. The afterlife of a recording career is not automatic. Master tapes must be located. Contracts must be interpreted. Licensing requests require someone authorized to answer them. Physical archives need storage and care. A family can inherit affection for an artist while lacking either the legal power or the intact collection needed to preserve the work.
At Twitty City, those problems could be seen in physical form. First the buildings changed hands. Then the collection dispersed. Only later could the heirs begin rebuilding a coherent public account from what remained.
What Twitty City Really Leaves Behind
Conway Twitty built the complex because records alone did not seem large enough to contain the relationship he had with his audience. He gave that relationship roads, gardens, a theater and a front gate.
After he died, the same concentration of property made the separation visible.
His mother and children left their homes. A television ministry acquired the land. Fans carried away objects packed into cars. His widow took a bidder number and paid for selected pieces. In court, the children bid for the rights that would allow Conway’s records and songs to keep moving under family control.
None of this altered the sound of “Hello Darlin’.” It altered who could look after it.
The auction tent eventually came down. The lots traveled to private collections. Twitty City received another name. But somewhere inside the probate record is the clearest measure of what Conway had built: even after the houses, furniture and stage clothes were assigned prices, the most valuable property was still the voice no room could hold.